1,300+ career closings · 267 Zillow reviews averaging 5.0 (October 2026) · Licensed in Arizona since 2002
James Sanson | Real Broker | Licensed in Arizona
Quick answer
How long does a short sale take in Maricopa? Most Maricopa short sale timelines run 90 to 180 days from listing day to closing. The lender's approval review is the longest single phase, typically 60 to 120 days. Preparation, marketing, and closing add another 60 to 90 days. A clean file with one loan and a cash buyer can close on the faster end. Complex files with second liens or slow servicers run past 180 days.
By James Sanson, REALTOR®. Licensed in Arizona since August 2002 and focused on the City of Maricopa since 2004. See the team's short sale credentials.
8 min read · Published May 15, 2026 · Updated September 29, 2026
How long does a short sale take in Maricopa? The most honest answer is that it depends, but the typical Maricopa short sale timeline runs 90 to 180 days from the day you list to the day you close. The factors that drive the spread are mostly outside your control, including your lender's approval procedures, your loan type, and whether complications arise during the file review. Some short sales close in under three months. Others stretch to six months or longer. This page walks through what to expect at each phase and what can speed or slow the clock.
If you have a specific deadline you are working against, call 520-838-8037 and we can talk through whether the timeline is realistic for your situation. The earlier in the process we have that conversation, the more options stay on the table.
The short answer: 90 to 180 days
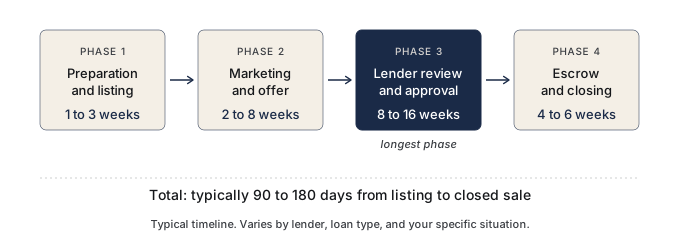
The typical Maricopa short sale closes 90 to 180 days after the property is listed. Within that range, the distribution is not even. Most deals fall in the 120 to 150 day band. A clean file with a single loan, a responsive lender, and a qualified buyer can close near 90 days. A complex file with a second mortgage, missing documents, or a slow servicer can run past 180 days.
The single biggest driver of variation is your lender's loss mitigation department. Some lenders are responsive, with clear procedures and reasonable review timelines. Others take weeks to respond to basic requests. The same loan type at two different servicers can produce very different timelines. We will tell you what to expect from your specific lender, based on what we have seen in past Maricopa short sales. Want a sharper estimate based on your situation? Call 520-838-8037.
Typical four-phase timeline of a Maricopa short sale. Total time varies by lender, loan type, and your specific situation.
Phase 1: Preparation and listing (1 to 3 weeks)
The preparation phase covers everything from your first call to the day the property hits the MLS. The work includes gathering your financial documents, drafting your hardship letter, getting the home market-ready, and preparing the listing materials.
Most of this phase is in your hands. If you have your documents organized and the home is showing condition, you can move in a week. If you need time to find tax returns from two years ago, locate the account numbers for a second mortgage, or schedule basic repairs, it can take up to three weeks. The faster you complete preparation, the faster the rest of the timeline runs. We can give you what paperwork your lender wants at the first conversation, so you can start gathering it immediately.
Phase 2: Marketing and offer (2 to 8 weeks)
Once the property is on the market, you wait for offers. In a balanced Maricopa market, well-priced short sales typically receive an acceptable offer within two to six weeks. In a slower market, or for properties priced too high relative to the lender's expected value, it can take longer.
Maricopa days on market for standard listings change month to month, and short sales tend to take about as long, or slightly longer, to attract acceptable offers because the buyer pool is narrower. Some buyers and agents skip short-sale listings because of the longer timeline and the uncertainty of lender approval. Others actively look for them. A skilled listing agent prices and presents the property to attract qualified buyers willing to pursue the short-sale process. Once you accept an offer, the file moves to the lender for review.
Phase 3: Lender approval (8 to 16 weeks, the long phase)
This is the phase that gives short sales their reputation for taking forever. Once the lender receives the complete package (your hardship documentation, the buyer's offer, plus all supporting paperwork), the loss mitigation review begins. A typical lender approval takes 60 to 120 days from package submission to approval letter.
During this window, the lender will order a Broker Price Opinion or appraisal, verify your hardship documentation, underwrite the deal, and decide whether to approve it as submitted or counter with different terms. If the lender wants a higher price, a contribution from you, or a promissory note to cover part of the shortfall, additional rounds of negotiation add time. For a deeper look at the lender approval process, including what BPO disputes look like and how counters get handled, see the dedicated page.
VA, FHA, conventional, and USDA loans each have different procedures here. FHA Pre-Foreclosure Sales follow a structured HUD program with relatively predictable timelines. Conventional loans through Fannie Mae or Freddie Mac follow agency guidelines but vary by servicer. VA Compromise Sales require Department of Veterans Affairs review as well as the servicer's. Your loan type sets a floor on how fast this phase can move.
Phase 4: Escrow and closing (4 to 6 weeks)
Once you have the lender's approval letter, the deal moves into escrow on a standard real estate closing track. The buyer finishes loan underwriting, the title company prepares closing documents, inspections wrap up, and a closing date is set. Cash buyers can close in two weeks. Financed buyers typically need four to six weeks.
The lender's approval letter usually specifies a closing deadline. If the deal does not close by that date, the approval expires, and the lender may require a new submission to extend. For the day-by-day breakdown of the final weeks, see the short sale closing process.
What can speed up or slow down your timeline?
Three things tend to make a Maricopa short sale faster than average. The first is complete and accurate documentation submitted on the first try. Any missing document or unclear line item can pause the lender's review, sometimes for days at a time. The second is a single-lien file. A property with only one mortgage closes faster than one with a second mortgage or a HELOC, in which two lenders must agree. The third is a cash buyer or a fully underwritten, financed buyer with no contingencies that can fall apart.
Common slowdowns include incomplete documentation, BPO or appraisal disputes (the lender's value comes in higher than the offer, and renegotiation is required), buyer financing falling through (forcing a relist and resubmission), and lenders with known slow loss-mitigation departments. The two factors most under your control are the documentation completeness and the listing price. Both are areas where an experienced short-sale real estate agent saves the most time.
Timing against an Arizona foreclosure clock
Many Maricopa homeowners considering a short sale are also racing against a foreclosure timeline. The two clocks interact. Arizona is a non-judicial foreclosure state, which means most foreclosures proceed through a trustee sale process governed by the Arizona Revised Statutes, Title 33. The full timeline typically runs from 110 to 180 days from the missed payment to the trustee sale. If your lender has already filed a Notice of Trustee Sale, you may have only 90 days before the sale date.
A pending short sale does not automatically pause foreclosure. The lender, not the listing agent, decides whether to delay the trustee sale while reviewing your short sale package. Many lenders will pause if a complete, credible short sale package is in front of them. Others will not. The earlier you start, the more runway you have. For a full breakdown of how foreclosure timing works in this state, see the Arizona foreclosure timeline.
If you are already in foreclosure, call 520-838-8037 today. Time matters, and the earlier in the foreclosure window we start, the more options remain on the table.
Common questions about Maricopa short sale timelines
The questions below come up in nearly every initial conversation about timing. If you have a specific deadline (a relocation date, a divorce timeline, a foreclosure sale date), bring that to the first call, and we can stress-test the timeline together. For impartial guidance before talking with us, you can request a housing counselor through HUD's referral program at no cost. Talk to our short sale team in Maricopa about your situation, and we will walk you through the short sale process from start to finish. Call 520-838-8037 to get started.
Last reviewed May 15, 2026, by James Sanson, REALTOR®. We review this guide on a recurring basis and update it for changes in lender procedures, Arizona foreclosure law, and Maricopa market conditions.
Tell us about your situation
No pressure, no obligation, no charge. James will call you back personally to discuss your options. For faster help, call 520-838-8037.
1,300+
Career Closings
267
Zillow Reviews, October 2026
22+
Years in Maricopa
5.0
Average Rating
Licensed since August 2002Maricopa focus since 2004Short sale experience since 2008
Meet the team
James personally handles every short sale listing he takes. David Hoos and David Ruiz are buyer specialists who help when our short sale listings need buyers, and David Ruiz also takes listings for sellers who prefer Spanish.
James Sanson
Listing Specialist, Lead Short Sale Negotiator
Licensed Arizona real estate agent since August 2002, focused on Maricopa since 2004. 1,300+ career closings. Built the short sale practice during the 2008-2012 downturn. Personally manages every short sale listing he takes.
David Hoos
Buyer Specialist
7 years in Maricopa. Works with buyers, including those writing offers on our short sale listings. Patient, thorough, answers the phone.
David Ruiz
Bilingual Buyer Specialist
Habla español. 8 years experience. Works with buyers across 85138 and 85139, including those writing offers on our short sale listings.
Frequently asked questions
Can a short sale close faster than 90 days?
Occasionally, yes. Cash buyers can compress the escrow phase, and some lenders with efficient loss mitigation can approve in 45 to 60 days. Even with both, the realistic floor on a Maricopa short sale is about 75 to 90 days because lender review takes time regardless of how prepared everyone else is. Most files that try to close faster end up with the lender extending the timeline anyway.
Does a missed payment speed up or slow down the timeline?
It depends on the lender. Some lenders will not begin a short sale review until you are delinquent, in which case waiting to miss a payment can delay things. Others will work with current homeowners but require documented imminent hardship. Never stop paying without first talking to a HUD-approved housing counselor or an attorney. The decision affects credit, taxes, and your options for the future.
My lender is taking forever. Is that normal?
Yes, in the sense that long lender response times are common in short sale loss mitigation departments. We push for updates regularly and escalate when files stall. If your specific lender or loan type has known long timelines (some have averages closer to four months for approval), we will tell you upfront so the expectation is realistic.
What if my buyer walks during the wait?
It happens. Buyer financing falls through, inspections turn up issues, or the buyer loses patience and finds another property. When that happens, the listing goes back active, we re-engage the marketing process, and once a new offer is in place we re-submit to the lender. The lender's prior review work usually transfers, so the second submission tends to move faster than the first.
Can I keep the timeline short by accepting the first offer?
Not really. Accepting an unrealistically low offer just guarantees the lender will counter or reject, which adds time rather than saving it. A defensible price for the lender, supported by recent comparable sales, is the fastest path to approval even if it means waiting a bit longer for the right offer.
Do I have to be in foreclosure for a short sale to make sense?
No. Many short sales are completed by homeowners who are still current on payments but can see clearly they will not be able to continue. Acting before foreclosure starts is generally better, not worse, because you have more time, more bargaining room with the lender, and less credit damage to manage.
What is the longest a short sale should reasonably take?
Six months is the upper end of typical. Beyond that, something specific is usually causing the delay (a second lien holder negotiation, a disputed appraisal, a buyer change). Files running past six months should be reviewed to identify the bottleneck. We do not let files drift indefinitely without addressing what is in the way.
Talk to a Maricopa specialist today
Behind on payments or weighing your options? Call James for a confidential conversation, with no pressure and no obligation.